Most travel insurance policies do not cover what you are about to do, and the two conditions that decide it are both yours rather than your operator’s.
This is the page the rest of this site keeps pointing at. Insurance comes up on nine other pages here because it comes up in every real conversation about this road, and it has never had a page of its own. It does now.
The short version
- The policy inside a tour price is not travel insurance. Ours is Bảo Việt with a 50,000,000₫ death benefit — about US$1,910. Read that second figure twice.
- It is a minimum-level policy and it is not a substitute for travel insurance. Buy your own before you arrive, and check the wording covers riding a motorbike.
- Two conditions void most claims here, and booking a guided tour fixes neither: whether you hold the licence your policy requires, and whether you were wearing a helmet.
- Search your policy document for four words before you pay for it. There is a section on which four and what the answers mean.
- What is properly covered is the bike. If it goes down and cannot be ridden, moving or replacing it is our cost rather than yours — that is real cover, and it is cover for the machine.
What the policy in your tour price actually is
We do carry a policy for you. Bảo Việt, the standard operator cover, with a death benefit of 50,000,000₫. It is a minimum-level policy and I would rather tell you that plainly: it is not travel insurance and it is not a substitute for travel insurance. So we ask every rider to buy their own before they arrive, and to check that it covers motorbikes.
Now the part no operator page does, and the reason this page is worth reading.
Convert it. At 26,179₫ to the US dollar — our own recorded rate from 20 August 2026 — a death benefit of 50,000,000₫ is about US$1,910.
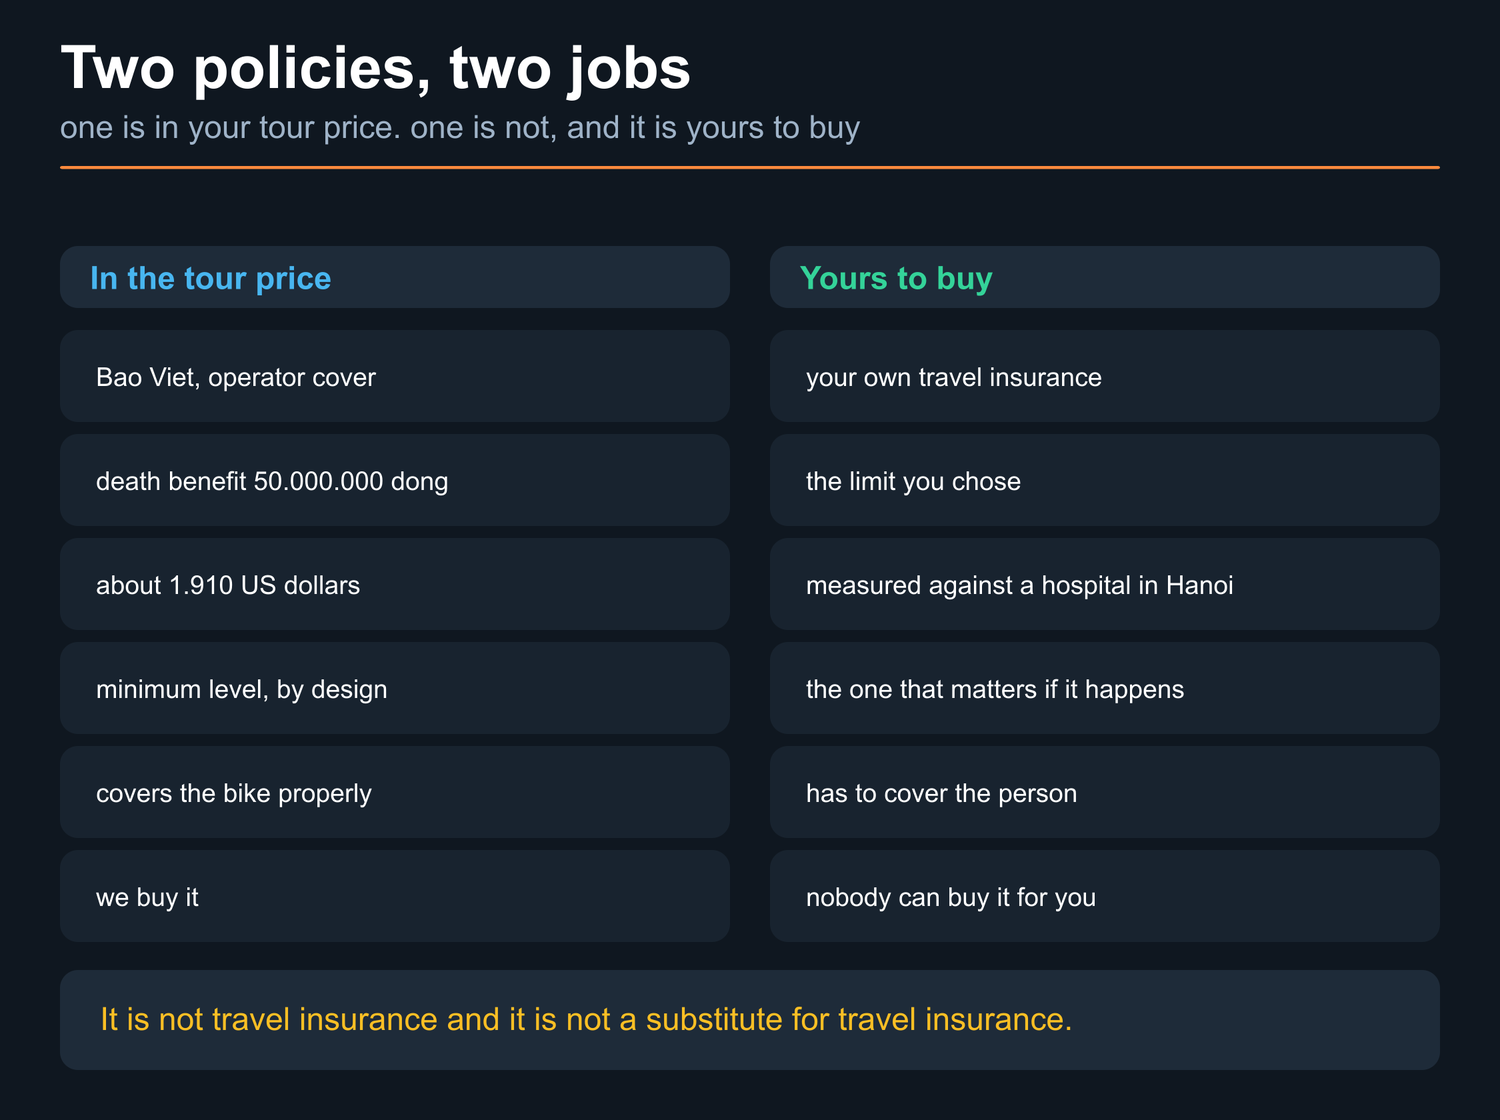
Fifty million dong is a number that sounds substantial in the currency it is written in. Nineteen hundred dollars is a number you can measure against an air ambulance, a hospital stay in Hanoi, or a flight home for somebody who has to come and get you. That is what “minimum-level” means, and it is why the sentence above is not false modesty.
I would rather you read the dollar figure on our page than work it out in a clinic.
What your own policy has to say
Open the policy document — the wording, not the marketing page — and search it for four things.
- “Motorcycle” or “motorbike”. If the word does not appear, that is not a good sign; it usually means a blanket exclusion sits somewhere else in the document. If it appears next to “excluded”, you have your answer.
- An engine-size limit. Many policies cover you up to a stated capacity and not above it. The bikes on this route are typically 125cc semi-automatics, which most limits clear — but if you have upgraded to a 150cc you have moved yourself, and you should know which side of the line that puts you on.
- A licence condition. This is the one that voids claims. Insurers commonly require that you are legally entitled to ride the machine in the country you are riding it in. Whether you are is settled by the permit and licence page, and it is settled before you leave home rather than at the roadside.
- A helmet condition. Some policies make it explicit. Wear one anyway, and wear one that fastens.
One specialist insurer publishes its Ha Giang requirements openly, and both the rider condition and the pillion conditions are quoted in full, with the read date, on the motorbike-tour page. I am not going to reproduce the wording twice on one site; go and read it there, because it is the clearest published statement of the licence link I have found.
The two conditions that void a claim
Everything above reduces to two facts about you, and neither of them changes because you booked a tour.
Your licence. The single fact that makes riding legal here is the same single fact your insurer asks about first. One gap, two consequences: a fine on the road, and a refused claim afterwards. Booking a guided trip does not license you, and no guide can ride your bike for you.
Your helmet. Straightforward, and the cheapest condition on the list to satisfy.
There is a third thing that is not a policy condition but behaves like one: whether you were the rider or the passenger. Cover for a pillion is a different question from cover for a rider, and if you have booked an easy-rider trip you are the passenger — that product has its own page and it works through what changes.
What is properly covered: the bike
There is one thing in the price that is genuine, uncomplicated cover, and it is worth being clear about because it is usually the line that gets misread.
The machine is covered. If a bike goes down and cannot be ridden, moving it or replacing it is our cost rather than yours. You are not going to be handed a bill for a bent frame at the end of a trip.
That is cover for the bike. It is not cover for the person on it, and an inclusion list that says only “insurance” has told you nothing about which of the two it means. Ask the question in those words — the bike, or me? — and the answer tells you a great deal about who you are dealing with.
Common questions
Does travel insurance cover motorbikes in Vietnam?
Often not, and rarely without conditions. Most policies either exclude motorcycles outright, cap the engine size they will cover, or require that you are legally entitled to ride in the country. Search the policy wording for “motorcycle”, for an engine-capacity limit and for a licence condition before you buy.
Is insurance included in a Ha Giang Loop tour?
An operator policy is. Ours is Bảo Việt with a 50,000,000₫ death benefit, which is roughly US$1,910 at 26,179₫ to the dollar. It is a minimum-level policy and it is not a substitute for travel insurance — buy your own and check it covers motorbikes.
What voids a motorbike insurance claim in Vietnam?
Most commonly, not holding the licence your insurer requires for the machine you were riding, and not wearing a helmet. Neither is something a tour company can fix for you; both are settled before you set off.
Am I covered as a passenger on an easy rider tour?
It is a different question from rider cover and it is worth asking your insurer specifically. Some policies impose conditions on the driver as well as on you.
Does the tour insurance cover damage to the motorbike?
Yes, and that part is real. If the bike goes down and cannot be ridden, moving or replacing it is our cost. That is cover for the machine and not for you.
Where the numbers come from. The insurer, the 50,000,000₫ death benefit and the scope of the damage cover are our own policy details, recorded 20 August 2026. The dollar figure is that number converted at 26,179₫ to the US dollar, the rate we recorded on the same day — it is arithmetic on our own figure rather than a separate claim, and the rate will have moved by the time you read this.
What is deliberately absent: any statement about how often claims of a given kind are paid or how long they take. I do not hold data I could stand behind on either, so this page describes what the cover is and leaves what it does in practice to your own insurer’s wording. Also absent: the licence rules, which belong to the permit page, and the fine bands, which belong to the motorbike-tour page.
Photographs taken on our own trips; each caption carries its own date. Diagrams and cards are ours.